Author: neashaminsuranceagency-com

  • Earn a 10% First-Year Credit—With Protection Built In

    Earn a 10% First-Year Credit—With Protection Built In

    A fixed index annuity may help balance growth potential with protection from market losses, while a 10% credit on the first-year deposit can enhance contract value when eligibility requirements are met. However, credits, interest, and guarantees depend on the specific insurer and contract terms. Review vesting schedules, caps, participation rates, surrender periods, fees, income provisions, insurer financial strength, and applicable state protections. Before purchasing, ask a licensed professional for a personalized illustration and confirm the strategy aligns with your time horizon, liquidity needs, and retirement objectives. This content is educational and not a guarantee or individualized financial advice.

    Continue to full article
  • American 401(K)S Are Moving Beyond Silos

    US workers increasingly wanted retirement planning that connected workplace 401(k)s with bank, investment, and advisor relationships, instead of keeping major savings inside separate systems.
    Industry leaders said 401(k)s stayed isolated because workplace plans, wealth management, advisors, and technology platforms developed separately, leaving broader financial planning disconnected.
    Connected platforms and data integration are beginning to give advisors fuller visibility, helping combine retirement accounts with other assets, goals, and day-to-day decisions.
    Advisors increasingly acted like financial quarterbacks, helping clients connect home equity, retirement savings, debt, healthcare, emergency reserves, and income planning into one strategy.
    The next phase depends on more participant control, open data sharing, and interoperability, with experts expecting retirement planning to merge into one coordinated experience.

  • Murder Mystery Night

    Murder Mystery Night

    Interactive Prohibition-era murder mystery at Stonehouse Cellars. Guests investigate clues, question characters, and try to identify the culprit.

    Continue to full article

  • Lifetime Income Options in 401(K)S Are Fading

    Traditional pensions once delivered lifelong monthly checks, but most US retirement savers now rely on accounts that show balances, not dependable income lasting through retirement.
    Among Americans 65+, guaranteed income from all sources fell from just over half of total retirement income in the early 2000s to ~43% by 2022.
    Many retirees wanted a dependable paycheck, and research found guaranteed income supported higher spending and greater retirement satisfaction while easing worries about outliving assets.
    Adoption stayed low because employers faced heavier burdens offering annuities, while savers often encountered information gaps, trust concerns, and complex choices too.
    Several bipartisan federal laws tried to expand workplace annuities, yet impact stayed limited: <10% of plans offered them, and participant uptake remained minimal.
    Future policy could boost adoption by easing employer liability and using default options that preserve flexibility, strengthening retirement secu

  • Annuities: Key Pros and Cons

    In the US, annuities exchange a lump sum or scheduled payments for regular income, often for life, while contributions grow tax-deferred inside the contract.
    Potential advantages include guaranteed payouts, fixed-return protection, index-linked contracts with a downside floor, and optional riders for inflation coverage, long-term care, or death benefits.
    Key tradeoffs include potentially high fees, seller commissions, and surrender periods of 3 to 10 yr, with early-exit charges that can start at ~7%.
    Buyers should also weigh ordinary-income taxes on gains, limited inflation protection on fixed payouts, and significant penalties when early access reduces liquidity.
    Common US annuities include fixed for predictable growth, variable for market-linked results, fixed-index with caps and floors, and immediate contracts starting payouts within 12 mo.
    In US retirement planning, building a tax-efficient income stream remains a priority, and an annuity may or may not fit that broader strate

  • Guaranteed Safe Returns? Think Twice

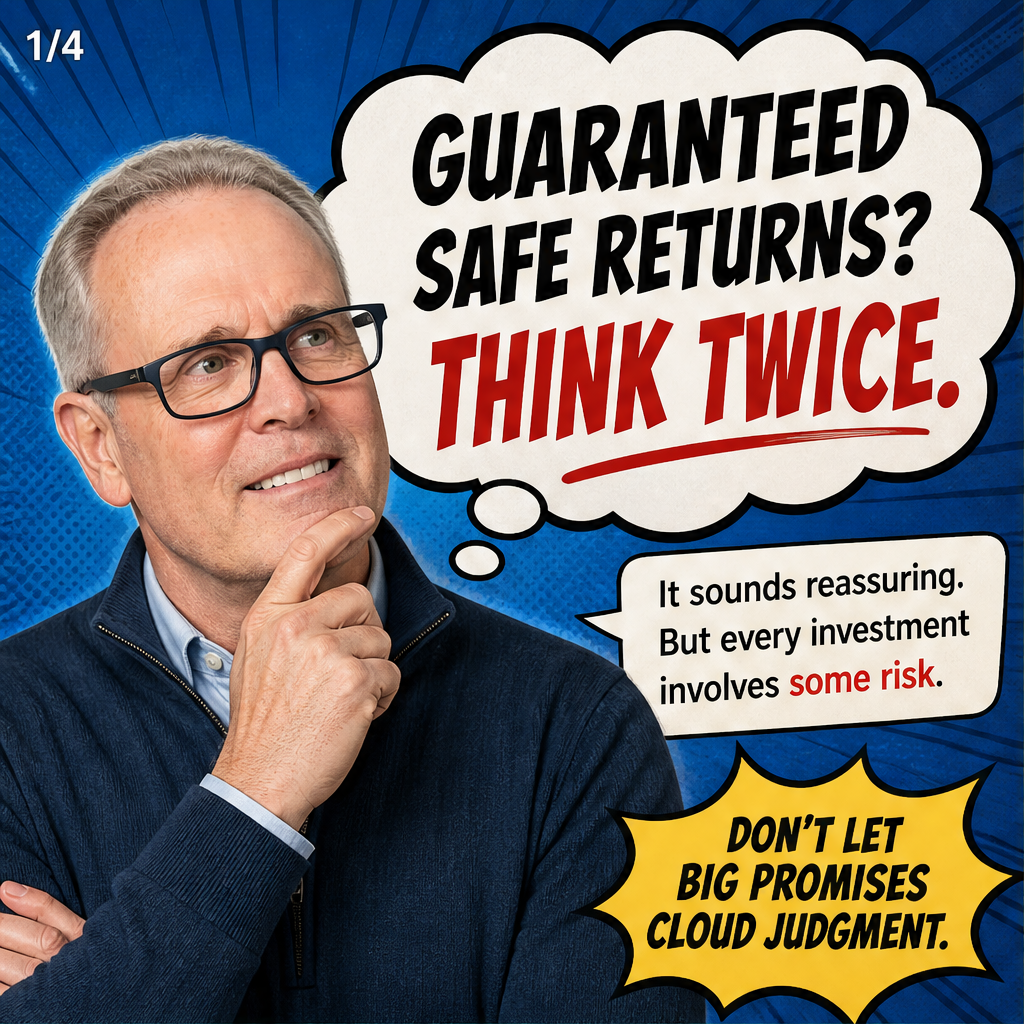
    Guaranteed Safe Returns? Think Twice

    “Guaranteed safe returns” can sound reassuring, but every investment involves some level of risk. Before investing, examine the fine print, identify who—if anyone—guarantees the outcome, and confirm whether protections or limits apply. Verify providers through SEC, FINRA, or state resources, compare promised returns with realistic market expectations, and watch for pressure tactics, vague strategies, and requests for unusual payment methods. A safer approach combines diversification, appropriate liquidity, clear goals, and independent professional guidance. This content is educational, not individualized financial advice.

    Continue to full article
  • “No Drop” Guided Ride- Six Sigma Ranch & Winery

    “No Drop” Guided Ride- Six Sigma Ranch & Winery

    Guided mountain-bike ride on Six Sigma Ranch trails hosted by Konocti Bicycles. The no-drop format is designed to keep riders together.

    Continue to full article

  • Retirement Planning for Older Parents

    Older parents often bring stronger careers, education, and existing retirement savings, but childcare, day-to-day family costs, and college bills can pressure long-term saving goals.
    When budgets feel tight, prioritize retirement contributions first. Children have more college funding options, including loans, work, community college, and family gifts available.
    Once parents pass age 50, portfolios should gradually take less risk. Keeping liquid emergency reserves also matters, especially if work ends earlier than expected.
    Protecting income is central: term life insurance can cover family needs more affordably, and disability coverage can help if health problems interrupt earnings.
    Long-term care and estate planning deserve early attention, especially guardians, powers of attorney, beneficiary designations, and trustee arrangements often needed for minor children.

  • Safe Returns vs. Risky Stocks: Build Wealth Without Betting It All

    Safe Returns vs. Risky Stocks: Build Wealth Without Betting It All

    Choosing between safer returns and risky stocks is not an all-or-nothing decision. Lower-volatility options may help protect money needed soon, while stocks can offer stronger long-term growth but may fall sharply. Start by matching risk to your time horizon and financial goals. Maintain an emergency fund, diversify across investments, and avoid putting too much capital into a single company or trend. Before making changes, review your risk tolerance and consider guidance from a qualified financial professional. Investing involves risk, including possible loss of principal.

    Continue to full article

  • Fixed Indexed Annuities: Build a More Predictable Retirement Strategy

    Fixed Indexed Annuities: Build a More Predictable Retirement Strategy

    Fixed indexed annuities can offer a combination of principal protection and interest potential linked to a market index, without directly investing in the market. However, results depend on contract features such as caps, participation rates, spreads, index choices, surrender periods, and optional income riders. This carousel explains the basics, highlights questions to ask, and encourages readers to compare policies carefully with guidance from a qualified financial professional. An FIA may be useful for some retirement objectives, but it is not right for everyone and does not eliminate inflation, insurer, or liquidity risks.

    Continue to full article