Author: neashaminsuranceagency-com

  • Protect Your Retirement Potential

    Protect Your Retirement Potential

    If you own an IRA, 403(b), or 401(k), you may be exploring ways to reduce market downside while keeping the opportunity for retirement income growth. Certain fixed indexed annuities can offer contractually defined protection features and may include an upfront premium credit, sometimes advertised as 25%. However, bonuses, guarantees, surrender periods, fees, participation rules, and tax treatment vary by product. Review the issuing carrier’s financial-strength ratings and read the contract carefully. A licensed professional can help compare options and determine whether a strategy aligns with your timeline, risk tolerance, and income goals. Guarantees depend on the claims-paying ability of the insurer.

    Continue to full article
  • Could a Bonus Annuity Fit Your Plan?

    Could a Bonus Annuity Fit Your Plan?

    A bonus annuity may offer an upfront first-year credit, indexed interest potential linked to benchmarks such as the S&P 500 and Nasdaq 100, and protection from direct market losses. Some contracts also include living benefits and a limited annual withdrawal provision. Before investing, review the guaranteed values, bonus vesting schedule, participation rates, caps, spreads, surrender charges, tax considerations, and withdrawal impact. Ask for a personalized illustration and confirm that all guarantees are backed by the issuing carrier’s claims-paying ability. Call or PM Glenn at 707-970-7315 for details.

    Continue to full article

  • Unlock Potential with a 25% Bonus FIA

    Unlock Potential with a 25% Bonus FIA

    A fixed indexed annuity may combine growth potential linked to selected market indexes with protection from market downturns, depending on contract terms. This concept features a potential 25% premium bonus, an illustrated 28.75% first-year yield, multiple index options, and benefits that may include nursing home, terminal illness, and critical illness provisions. Some contracts also allow 5% free annual withdrawals and beneficiary or POD features. Actual guarantees, charges, surrender schedules, eligibility, and bonus vesting vary by carrier and state. Review the full policy and consult a licensed professional before making a decision.

    Continue to full article

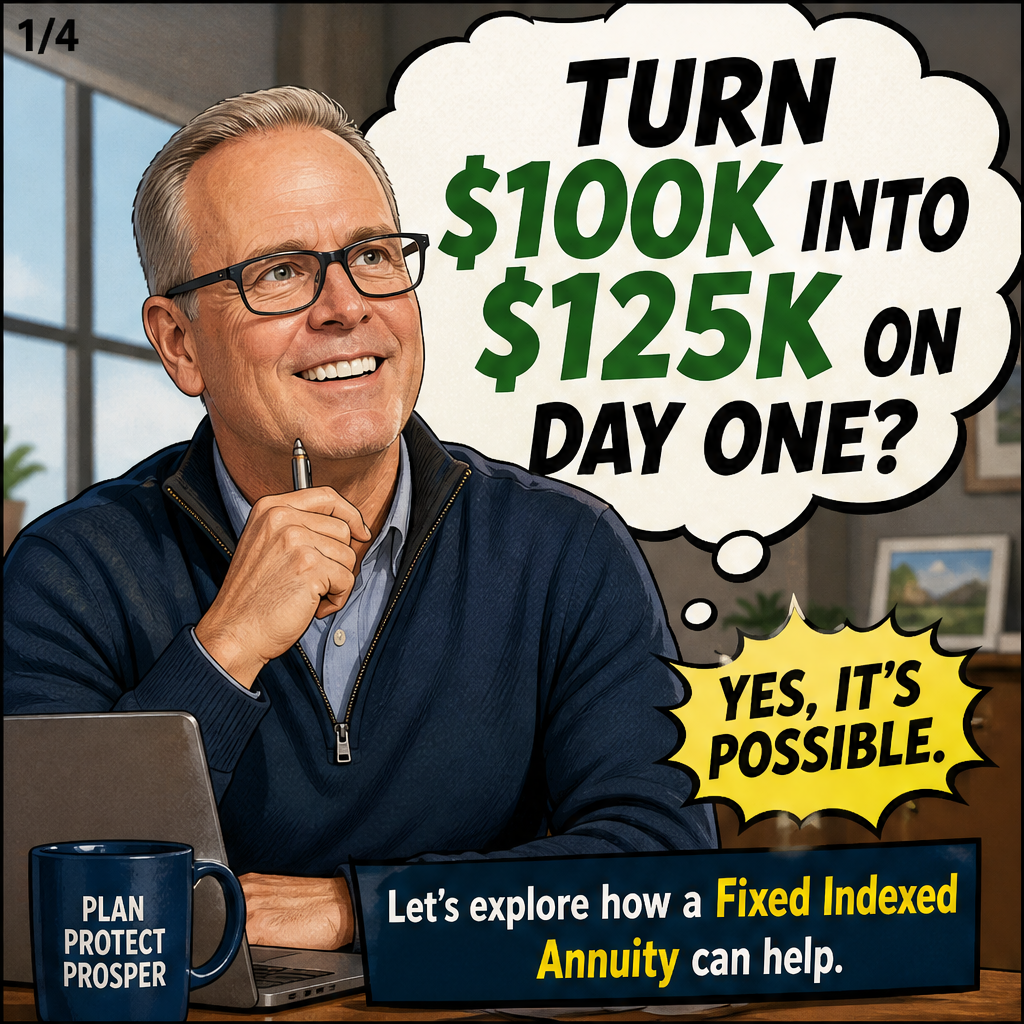
  • Turn $100K Into $125K on Day One? Explore a Fixed Indexed Annuity with Protected Growth

    Turn $100K Into $125K on Day One? Explore a Fixed Indexed Annuity with Protected Growth

    A fixed indexed annuity may help retirement savers pursue protected growth and future income. Some contracts offer a premium bonus—potentially turning a qualifying $100,000 contribution into $125,000 in contract value on day one—subject to vesting, surrender schedules, fees, and other terms. These products may also include index-linked interest, 5% annual free withdrawals, and living-benefit riders. They can be considered for assets from 401(k)s, 403(b)s, IRAs, or other conservative strategies, but they are not risk-free in every respect: withdrawals, taxes, inflation, caps, spreads, liquidity limits, and insurer guarantees matter. Consult a qualified advisor and review the full contract before investing.

    Continue to full article

  • Why Millennials and Gen Z are Taking Micro-Retirements—and How You Can Too

    Why Millennials and Gen Z are Taking Micro-Retirements—and How You Can Too

    I've been in the insurance world for over 30 years, and it's fascinating to watch how Millennials and Gen Z are reshaping the idea of retirement. Many are now opting for "micro-retirements"—taking a few months off to recharge and focus on their well-being. It’s not just about hitting pause; it takes thoughtful planning, building up savings with at least a 20% cushion, making sure you’re covered with health insurance, and being able to communicate your time away to employers. I see these steps not only strengthening financial security, but also contributing to long-term career satisfaction. As someone who’s helped clients protect their future with annuities and universal life, I appreciate how intentional planning can open doors to flexibility—whether you’re taking a break now or preparing for the years ahead.

    Continue to full article

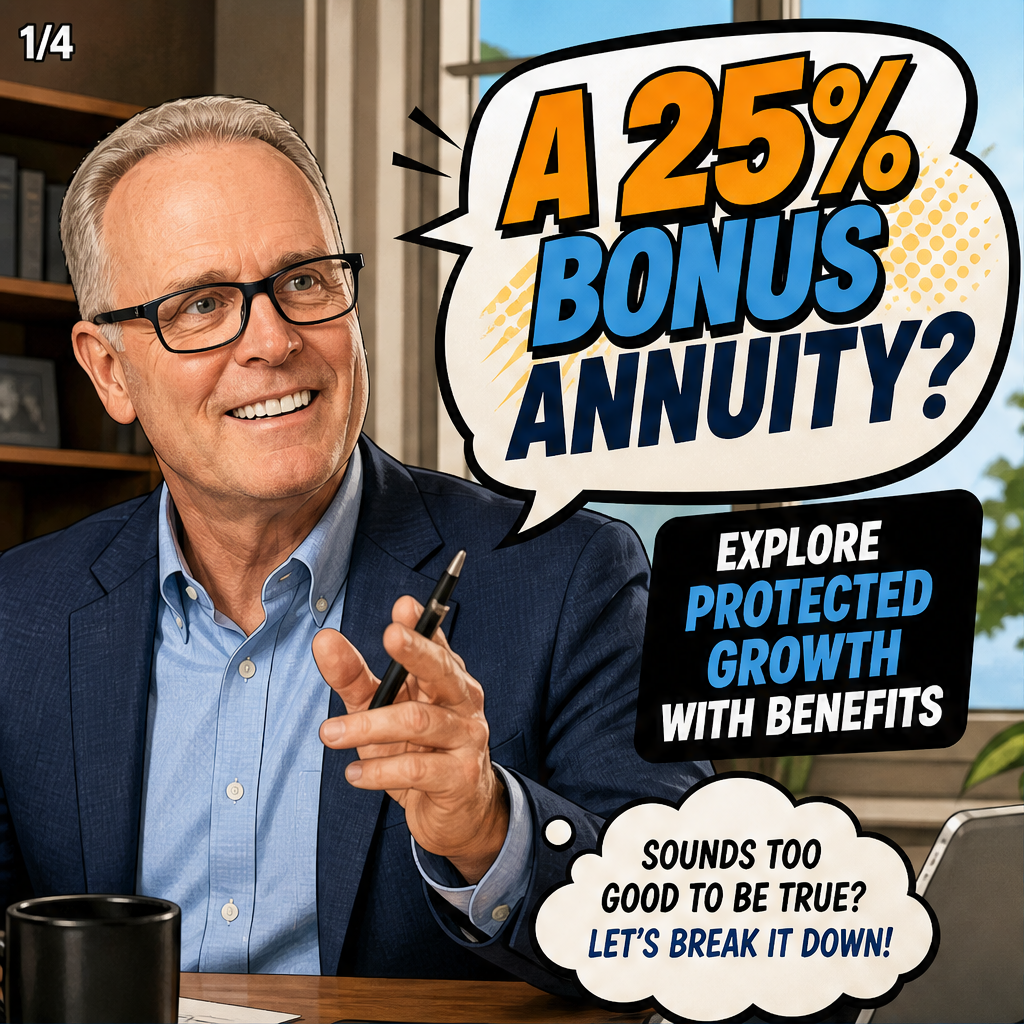
  • A 25% Bonus Annuity? Explore Protected Growth With Benefits

    A 25% Bonus Annuity? Explore Protected Growth With Benefits

    A bonus fixed indexed annuity may offer an initial premium bonus, index-linked interest potential, and protection from direct market losses. In this example, a $100,000 contribution could show a $125,000 initial account value, while a stated 28.75% first-year yield depends on the contract’s definition, crediting method, caps, participation rates, and bonus provisions. Some contracts may also include a 4.50% fixed account option, 5% annual free withdrawals, and nursing-home, terminal-illness, or critical-illness benefits. Investors should review surrender schedules, fees, tax treatment, liquidity limits, carrier strength, and all guarantees with a qualified fiduciary before purchasing. Guarantees depend on the issuing insurer’s claims-paying ability.

    Continue to full article

  • Average Retirement Savings by Age: How Do You Compare?

    Average Retirement Savings by Age: How Do You Compare?

    Average retirement savings in the U.S. vary by age: 30s have $18,000–$35,000, 40s $60,000–$100,000, 50s $134,000–$185,000, and early 60s $200,000–$250,000. Medians hide inequality, as high earners raise averages while many have little saved. Recommended savings benchmarks suggest having 1x salary by 30, 3x by 40, 6x by 50, 8x by 60, and 10x by retirement. Strategies to boost savings include maximizing contributions, reducing expenses, delaying retirement, and optimizing Social Security and investments.

    Continue to full article

  • Die With Zero Needs a Plan

    The spend-it-all retirement mindset appeals because some retirees underspend, while memorable experiences and giving can create lasting emotional value throughout later life.
    Planning matters: a current survey found ~50% of Americans lack a written financial plan, and advisers said this strategy demands deliberate budgeting and savings.
    Many retirees already withdraw less than the traditional ~4% guideline, and past research found some households still held all their starting retirement assets later.
    Spending and gifting earlier can reduce tax efficiency, because bigger withdrawals may trigger taxes and heirs can lose a valuable step-up in basis.
    One adviser recommended permanent life insurance bought earlier, so spenders can leave heirs a tax-free benefit and tap policy value if needed.

  • YPN- Golf Mixer

    YPN- Golf Mixer

    Young Professionals Network golf mixer featuring golf, networking, and raffle prizes at Greenview Golf Course.

    Continue to full article

  • Earn $9,400 Monthly: Grow Dividend Income Effortlessly

    Earn $9,400 Monthly: Grow Dividend Income Effortlessly

    To generate $112,800 annually in dividend income, capital needs vary by yield tier: conservative (3.5% yield) requires about $3.22 million, moderate (6% yield) about $1.88 million, and aggressive (10.6% yield) roughly $1.06 million. Higher yields reduce capital needed but risk income cuts and less growth. A blended portfolio balances growth and yield, needing around $1.41 million. Focus on actual spending, stress-test high-yield assets, and compare total returns over yields.

    Continue to full article