Blog

  • Why Millennials and Gen Z are Taking Micro-Retirements—and How You Can Too

    Why Millennials and Gen Z are Taking Micro-Retirements—and How You Can Too

    I've been in the insurance world for over 30 years, and it's fascinating to watch how Millennials and Gen Z are reshaping the idea of retirement. Many are now opting for "micro-retirements"—taking a few months off to recharge and focus on their well-being. It’s not just about hitting pause; it takes thoughtful planning, building up savings with at least a 20% cushion, making sure you’re covered with health insurance, and being able to communicate your time away to employers. I see these steps not only strengthening financial security, but also contributing to long-term career satisfaction. As someone who’s helped clients protect their future with annuities and universal life, I appreciate how intentional planning can open doors to flexibility—whether you’re taking a break now or preparing for the years ahead.
    Continue to full article

  • A 25% Bonus Annuity? Explore Protected Growth With Benefits

    A 25% Bonus Annuity? Explore Protected Growth With Benefits

    A bonus fixed indexed annuity may offer an initial premium bonus, index-linked interest potential, and protection from direct market losses. In this example, a $100,000 contribution could show a $125,000 initial account value, while a stated 28.75% first-year yield depends on the contract’s definition, crediting method, caps, participation rates, and bonus provisions. Some contracts may also include a 4.50% fixed account option, 5% annual free withdrawals, and nursing-home, terminal-illness, or critical-illness benefits. Investors should review surrender schedules, fees, tax treatment, liquidity limits, carrier strength, and all guarantees with a qualified fiduciary before purchasing. Guarantees depend on the issuing insurer’s claims-paying ability.

    Continue to full article

  • Average Retirement Savings by Age: How Do You Compare?

    Average Retirement Savings by Age: How Do You Compare?

    Average retirement savings in the U.S. vary by age: 30s have $18,000–$35,000, 40s $60,000–$100,000, 50s $134,000–$185,000, and early 60s $200,000–$250,000. Medians hide inequality, as high earners raise averages while many have little saved. Recommended savings benchmarks suggest having 1x salary by 30, 3x by 40, 6x by 50, 8x by 60, and 10x by retirement. Strategies to boost savings include maximizing contributions, reducing expenses, delaying retirement, and optimizing Social Security and investments.

    Continue to full article

  • YPN- Golf Mixer

    YPN- Golf Mixer

    Young Professionals Network golf mixer featuring golf, networking, and raffle prizes at Greenview Golf Course.

    Continue to full article

  • Die With Zero Needs a Plan

    Die With Zero Needs a Plan

    The spend-it-all retirement mindset appeals because some retirees underspend, while memorable experiences and giving can create lasting emotional value throughout later life.
    Planning matters: a current survey found ~50% of Americans lack a written financial plan, and advisers said this strategy demands deliberate budgeting and savings.
    Many retirees already withdraw less than the traditional ~4% guideline, and past research found some households still held all their starting retirement assets later.
    Spending and gifting earlier can reduce tax efficiency, because bigger withdrawals may trigger taxes and heirs can lose a valuable step-up in basis.
    One adviser recommended permanent life insurance bought earlier, so spenders can leave heirs a tax-free benefit and tap policy value if needed.

  • Earn $9,400 Monthly: Grow Dividend Income Effortlessly

    Earn $9,400 Monthly: Grow Dividend Income Effortlessly

    To generate $112,800 annually in dividend income, capital needs vary by yield tier: conservative (3.5% yield) requires about $3.22 million, moderate (6% yield) about $1.88 million, and aggressive (10.6% yield) roughly $1.06 million. Higher yields reduce capital needed but risk income cuts and less growth. A blended portfolio balances growth and yield, needing around $1.41 million. Focus on actual spending, stress-test high-yield assets, and compare total returns over yields.

    Continue to full article

  • Earn a 10% First-Year Credit—With Protection Built In

    Earn a 10% First-Year Credit—With Protection Built In

    A fixed index annuity may help balance growth potential with protection from market losses, while a 10% credit on the first-year deposit can enhance contract value when eligibility requirements are met. However, credits, interest, and guarantees depend on the specific insurer and contract terms. Review vesting schedules, caps, participation rates, surrender periods, fees, income provisions, insurer financial strength, and applicable state protections. Before purchasing, ask a licensed professional for a personalized illustration and confirm the strategy aligns with your time horizon, liquidity needs, and retirement objectives. This content is educational and not a guarantee or individualized financial advice.

    Continue to full article

  • American 401(K)S Are Moving Beyond Silos

    American 401(K)S Are Moving Beyond Silos

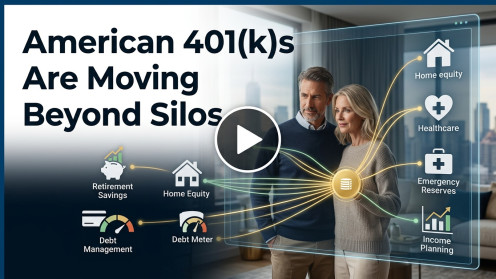
    US workers increasingly wanted retirement planning that connected workplace 401(k)s with bank, investment, and advisor relationships, instead of keeping major savings inside separate systems.
    Industry leaders said 401(k)s stayed isolated because workplace plans, wealth management, advisors, and technology platforms developed separately, leaving broader financial planning disconnected.
    Connected platforms and data integration are beginning to give advisors fuller visibility, helping combine retirement accounts with other assets, goals, and day-to-day decisions.
    Advisors increasingly acted like financial quarterbacks, helping clients connect home equity, retirement savings, debt, healthcare, emergency reserves, and income planning into one strategy.
    The next phase depends on more participant control, open data sharing, and interoperability, with experts expecting retirement planning to merge into one coordinated experience.

  • Murder Mystery Night

    Murder Mystery Night

    Interactive Prohibition-era murder mystery at Stonehouse Cellars. Guests investigate clues, question characters, and try to identify the culprit.

    Continue to full article

  • Lifetime Income Options in 401(K)S Are Fading

    Lifetime Income Options in 401(K)S Are Fading

    Traditional pensions once delivered lifelong monthly checks, but most US retirement savers now rely on accounts that show balances, not dependable income lasting through retirement.
    Among Americans 65+, guaranteed income from all sources fell from just over half of total retirement income in the early 2000s to ~43% by 2022.
    Many retirees wanted a dependable paycheck, and research found guaranteed income supported higher spending and greater retirement satisfaction while easing worries about outliving assets.
    Adoption stayed low because employers faced heavier burdens offering annuities, while savers often encountered information gaps, trust concerns, and complex choices too.
    Several bipartisan federal laws tried to expand workplace annuities, yet impact stayed limited: <10% of plans offered them, and participant uptake remained minimal.
    Future policy could boost adoption by easing employer liability and using default options that preserve flexibility, strengthening retirement secu