Category: Latest Posts

  • Chili, Community & Wine

    Chili, Community & Wine

    Spice up your calendar with an all-day Chili Cookoff at Wild Diamond Vineyards in Hidden Valley Lake, California, on Saturday, September 26th. Whether you are entering your famous recipe or simply arriving hungry, everyone is welcome to come as they are. Bring the whole family for a relaxed day of flavorful competition, local community, and vineyard hospitality. Gather your friends, prepare your best chili, and make plans to enjoy a memorable event at Wild Diamond Vineyards.

    Continue to full article
  • Chili, Wine & Family Time!

    Chili, Wine & Family Time!

    Get ready for a flavorful day at Wild Diamond Vineyards! On September 26, 2026, Hidden Valley Lake, California, will welcome families and food lovers for an all-day chili cookoff. Bring the whole family to enjoy creative chili, friendly competition, vineyard atmosphere, and quality time with the community. Use this event as your reason to gather loved ones, plan a memorable outing, and celebrate great food together. Mark your calendar, share the invitation, and make plans to join the fun at Wild Diamond Vineyards.

    Continue to full article
  • US Annuities for Retirement Income

    After more than 30 years guiding clients at Neasham Insurance Agency, I’ve seen how annuities can be a valuable tool for retirement planning. Annuities are insurance contracts designed to provide guaranteed income, with options for immediate or deferred payouts. Depending on the type—fixed, variable, or indexed—your growth potential and risk exposure will vary. Fixed annuities guarantee a set return, variable annuities fluctuate with the market, and indexed annuities tie growth to a market index, offering a balance between security and potential. It’s important to remember that not every annuity suits every retiree; fees, surrender periods, and withdrawal penalties all play a role in what’s best for you. For those who prefer stability, annuities can help transform a portion of your savings into a reliable income stream, making retirement budgeting more predictable and easing concerns about outliving your assets. With options starting at $1,000 and extending up to age 85, it’s worth taking the time to match features and fees to your specific needs. My experience has shown that careful planning can make all the difference in building a retirement you can count on.

  • QLAC Income Can Wait Until Age 85

    For those exploring ways to manage retirement distributions, here’s a QLAC strategy that might fit the bill. If a 72-year-old moves $210K into a Qualified Longevity Annuity Contract (QLAC) before year-end, next year’s required minimum distribution (RMD) drops by about $7,900, potentially lowering federal taxes by $1,700. That’s because the funds in a QLAC aren’t counted in the IRA balance for next year’s RMD calculation.

    This approach is best suited to retirees who have surplus IRA assets, other liquid savings, and a family history of longevity—especially if a lower RMD helps in managing Medicare premium thresholds. Of course, there are tradeoffs: once the money is in a QLAC, it’s generally locked up until income begins (which can be deferred as late as age 85), and future payouts are taxable income.

    Current long-term yields may make deferred income options more attractive than in the past, so it’s worth comparing lifetime payout guarantees, death benefit features, and income start dates. With over 30 years at Neasham Insurance Agency, I make it a point to help clients weigh these options carefully to align with their broader retirement goals.

  • Annuity Breakthrough: Grow, Protect, Transfer

    Annuity Breakthrough: Grow, Protect, Transfer

    For savers comparing bank CDs, stocks, bonds, and mutual funds, an annuity may offer a different approach to long-term accumulation. Depending on the contract, a fixed annuity can provide guaranteed interest, tax-deferred growth, and a death benefit for named beneficiaries. Some contracts may offer rates above traditional CDs, but results vary and guarantees depend on the issuing insurer’s claims-paying ability. Annuities can also include surrender charges, tax considerations, and limited liquidity. Review the contract carefully and compare options with a qualified financial professional to determine whether the strategy fits your goals.

    Continue to full article

  • 6.15% Guaranteed for 5 Years: Explore a Safer, Tax-Deferred Option

    6.15% Guaranteed for 5 Years: Explore a Safer, Tax-Deferred Option

    A five-year fixed annuity offering 6.15% may appeal to people seeking predictable growth and tax-deferred accumulation. Unlike a bank deposit, an annuity is an insurance product, so guarantees depend on the issuing insurer’s claims-paying ability and applicable state guaranty association rules—not FDIC insurance. Interest rates, surrender charges, withdrawal limits, renewal terms, and tax treatment all matter. Compare the contract with CDs, savings accounts, and money market options, and consult a licensed financial or tax professional before making a decision. Product availability and protections vary by state.

    Continue to full article

  • A 25% Bonus—With Questions to Ask First

    A 25% Bonus—With Questions to Ask First

    A 25% premium bonus may sound compelling, especially when paired with guaranteed monthly income options and market-linked growth potential. However, the details matter: bonuses can involve vesting schedules, surrender periods, fees, participation limits, caps, spreads, and contract-specific conditions. Insurance guarantees depend on the issuing carrier’s financial strength, while “no downside risk” generally applies only under defined contract terms and does not mean every outcome is risk-free. Before acting, compare highly rated carriers, review the complete policy, and discuss your goals with Glenn Neasham, a fiduciary advisor, to determine whether the strategy suits your retirement plan.

    Continue to full article

  • Retirement Income, Built With Care

    Retirement Income, Built With Care

    Retirement planning requires more than focusing on a bonus or a “no-risk” message. Some fixed indexed annuities may provide an upfront premium bonus, tax-deferred growth potential, lifetime-income options, and limited annual withdrawals. However, guarantees depend on the issuing insurer’s financial strength, and contracts may include surrender charges, fees, participation limits, market-value adjustments, tax considerations, and restrictions on bonuses or withdrawals. Before making a decision, compare alternatives and ask a fiduciary to explain how the strategy supports your income needs, liquidity, legacy goals, and risk tolerance. Always review the complete contract and disclosures.

    Continue to full article

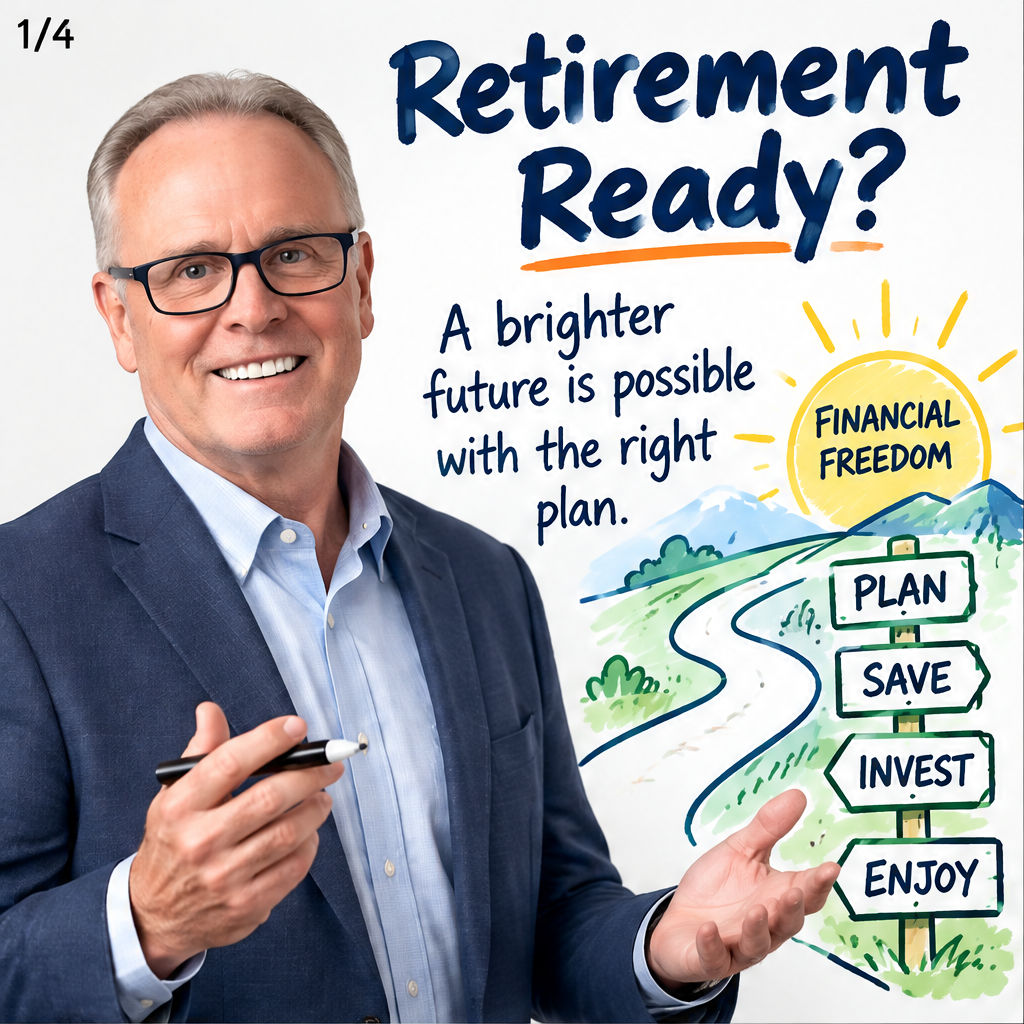
  • Retirement Ready: 4 Smart Moves for Your Future

    Retirement Ready: 4 Smart Moves for Your Future

    Retirement planning becomes easier when you turn a distant goal into practical steps. Start by estimating how much income you may need and when you want to retire. Then take advantage of employer matching contributions, which can significantly strengthen your savings. Build a diversified portfolio that reflects your timeline and comfort with risk, and revisit it as your circumstances change. Finally, commit to one action today—such as increasing your contribution, checking your account, or scheduling a professional review. Small, consistent decisions can help create greater financial confidence for the future.

    Continue to full article

  • Turn Savings Into Steady Income

    Turn Savings Into Steady Income

    After more than 30 years helping clients make the most of their savings, I’ve found that clarity is the first step toward reliable income. If you’re considering annuities as a way to create steady monthly income, start by defining your goal: estimate exactly how much you’d like to receive each month, and when you’ll want that income to begin. This simple groundwork can make all the difference as you navigate your options and set yourself up for financial confidence.

    Continue to full article